Startups
Egypt’s Fintech enza Raises $6 Million to Expand Across Africa

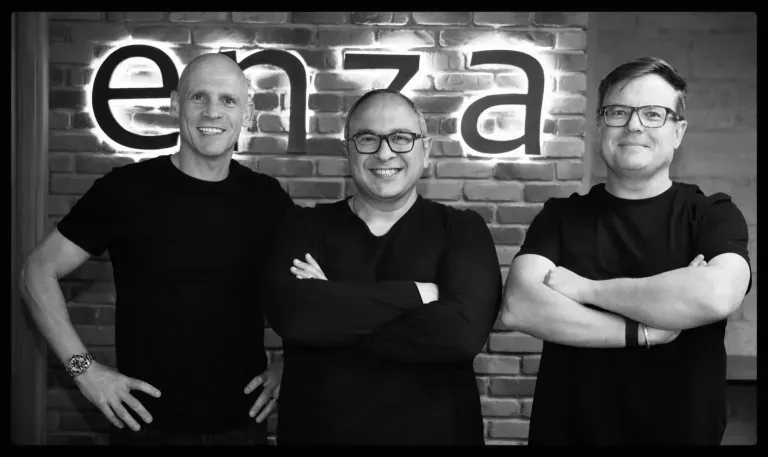
Payments infrastructure provider enza has secured $6 million in a Seed+ funding round led by 4DX Ventures, with British International Investment joining as a new investor. The company plans to expand its services across Africa, where it currently serves banks and fintechs in 12 countries.
[For more news, click here]
Africa’s digital payments industry has expanded rapidly, but many banks still rely on systems that were not designed to support today’s growing mix of payment methods.
From mobile wallets and instant transfers to local card networks, financial institutions increasingly need to connect multiple services while maintaining control over transactions, customer relationships and regulatory compliance.
The demand for more flexible payment infrastructure is attracting new investment, including a $6 million funding round secured by Abu Dhabi-based fintech enza.
The company, which provides payment processing technology to banks and fintech businesses across Africa, announced the Seed+ round on November 3.
The investment was led by 4DX Ventures, with British International Investment (BII), the UK’s development finance institution, joining as a new investor.
Existing backers Quona Capital and Egypt-based Algebra Ventures also increased their investments. Both firms previously co-led enza’s $6.75 million seed round in March 2025.
The latest funding brings enza’s publicly announced fundraising across the two rounds to $12.75 million.
Expanding Payments Infrastructure Across Africa
Founded in 2023, enza develops infrastructure that allows financial institutions to introduce and manage different payment services without building separate systems for each channel.
The company says Its platform connects banks and fintechs to payment networks through a single integration while allowing them to retain control of their merchant relationships and transaction data.
Its services cover card payments, mobile wallets, real-time transfers, online payment gateways and merchant acquiring.
According to earlier TechCrunch reporting enza’s technology supports connections to domestic payment systems such as Egypt’s Meeza and InstaPay, Nigeria’s NIBSS and South Africa’s PayShap, alongside international networks including Visa and Mastercard.
The company also offers AI-powered fraud detection through enzaGuard and payment cost-management tools through enza Optimizer.
These capabilities are intended to help banks introduce new services without replacing every component of their existing technology infrastructure.
Hany Fekry, Group CEO of enza, said:
“Since our launch, we have been building the payments infrastructure partner African banks and fintechs have been missing.”
The company currently serves banking and fintech clients across 12 African countries, according to its funding announcement.
New Investment to Support Licensing and Product Development
The new capital will support entry into additional African markets, including obtaining the regulatory licences required to provide payment services.
It will also finance further development of enza’s product portfolio.
The company has not identified all the countries it plans to enter next or disclosed how much of the funding will be allocated to individual markets.
Its expansion strategy depends partly on navigating different regulatory frameworks, as payment providers typically need local authorisation before offering certain services.
Ghana provides a recent example.
In June 2026, enza announced that it had received a Payment Service Provider Enhanced licence from the Bank of Ghana.
The company subsequently launched its operations in the country in September, creating a regulatory foundation for working with local financial institutions and fintech businesses.
Enza is headquartered in Abu Dhabi, with regional operations in Egypt, South Africa, Ghana and Nigeria.
Its leadership includes former executives from Network International and Emerging Markets Payments, bringing experience in payment processing across African markets.
Why African Banks Need Modern Payment Systems
Digital financial services have expanded significantly across Africa, driven partly by mobile money adoption and the increasing availability of electronic payments.
According to the World Bank’s Global Findex 2025 report, 58% of adults in Sub-Saharan Africa had an account at a financial institution or mobile money provider in 2024, compared with 49% in 2021.
However, growing access to digital financial services does not eliminate the infrastructure challenges faced by banks and payment providers.
Financial institutions must support different domestic networks, payment methods and regulatory requirements, often across markets with limited interoperability.
For companies such as enza, this creates demand for infrastructure that connects financial institutions to multiple payment channels without requiring them to develop every integration independently.
The business model also reflects a broader shift in African fintech, where technology companies increasingly provide services directly to established banks rather than competing exclusively for consumer accounts.
The Challenge of Scaling Across Multiple Markets
Despite its expanding presence, enza faces the operational complexity of serving financial institutions in countries with different payment rules, currencies and technical standards.
Its ability to grow will depend on securing regulatory approvals, integrating with local payment systems and maintaining reliable processing services.
The company has not disclosed its valuation following the latest round, annual revenue or current transaction volumes.
These figures would provide a clearer picture of its commercial performance as the business expands.
The participation of BII and returning investors gives enza additional capital to pursue its plans, but the larger test will be whether it can convert its existing relationships and technology into sustainable growth across more African markets.
As digital payments become more widely used, the infrastructure connecting banks, merchants and payment networks is becoming an increasingly important part of Africa’s financial technology industry.